EPISODE SUMMARY
You probably know what you paid for your home. You may even have a rough idea what it’s worth today. But does that number actually tell you whether your home has been a good investment?
In this episode, Beth Dodson sits down with John Bodrozic to go well beyond the Zestimate. Together they unpack the full financial picture of homeownership — purchase price, equity, loan-to-value ratio, mortgage interest, property taxes, maintenance, remodels, tax basis, closing costs, and annualized return — and then add the piece almost every online debate leaves out: the lifestyle return.
John shares the real numbers from his first home (bought around $250K, sold roughly eight years later near $400K) and uses it as a working example to walk through how equity actually builds, why paying down principal is itself an investment decision, and why a $30,000 kitchen remodel almost never returns dollar for dollar. Beth pushes back productively throughout — particularly on maintenance, arguing that while the tax code calls it an expense, extending the life of your HVAC, appliances, and building materials protects your bottom line in a way spreadsheets don’t always capture.
The conversation also tackles the social-media narrative that “a home is a bad investment.” John’s counterpoint: those 10-second takes ignore risk profile entirely, and no stock portfolio has ever given anyone a bed to sleep in or a kitchen to cook in.
The episode closes with a practical, three-step framework any homeowner can start this week — gather your scattered financial data, run the basic calculations, and layer in your honest lifestyle needs.
Note: Neither Beth nor John is a financial advisor, tax attorney, or real estate professional. This episode is informational and educational — listeners are encouraged to consult their own tax and financial professionals.
TOPIC BREAKDOWN
00:42 — Opening: The question behind the question Beth frames the episode. You know what you paid and roughly what it’s worth — but what about improvements, principal paydown, maintenance, taxes, insurance, and the value of simply having a place to live?
01:46 — Does John consider his primary home an investment? An unqualified yes. Writing a down payment check is cash out of your net worth going onto a physical asset — which makes it a primary investment by definition.
02:49 — The first-house case study John’s real numbers: purchased around $250K, sold roughly eight years later near $400K. He’s candid that the appreciation wasn’t something he engineered — good neighborhood, strong economy, in-migration.
03:37 — Supply, demand, and neighborhood scarcity Beth connects appreciation to basic business fundamentals. Limited availability in a desirable community drives value; a neighborhood with many simultaneous listings invites comparison shopping.
05:00 — What’s missing from “I sold it for more than I paid” The costs almost nobody subtracts: mortgage interest, ongoing maintenance and repairs, property taxes, utilities. John contrasts his physical home asset with the digital assets in his portfolio.
06:12 — Interest rates, then and now John’s first mortgage was around 7.5% — and he thought he’d gotten a great deal. Useful perspective on the current rate conversation.
07:11 — The tax code relationship Mortgage interest deductibility as a partial offset to the ongoing expense load.
07:47 — Furnishings as part of your asset portfolio Beth’s argument that furniture, collectibles, and personal property travel with you and belong in the broader picture.
09:26 — Why homeowners fixate on valuation — and what they should watch instead Beth challenges the obsession with real estate portal estimates.
10:26 — Equity explained: the two-slice pie Current value minus remaining principal. Every financed home is a pie with two slices — yours and the bank’s. Your goal is a growing pie and a shrinking bank slice.
12:06 — Pay it off or leverage it? Two philosophies Beth lays out the split among their own friends: own outright and be debt-free, versus borrow against equity when the rate beats other financing options.
13:33 — Loan-to-value ratio, worked through with numbers John defines LTV, walks the math, and explains why most lenders want you below roughly 80% before they’ll extend a home equity loan or line.
14:22 — The 2008 reference Beth’s pointed reminder of what happens when borrowers get overextended.
14:44 — The $50,000 bonus question Put it toward principal or invest it elsewhere? John explains the two possible outcomes of a principal prepayment — lower monthly payment with the same term, or same payment with a shorter payoff.
16:34 — The column nobody analyzes: risk Everyone asks about return. Almost nobody asks about risk. The Vegas roulette comparison begins here.
18:53 — Visualizing the free-and-clear day What it actually means to own outright: zero LTV, no mortgage payment, and maximum home-equity borrowing capacity.
20:18 — Equity in retirement: callback to prior episodes Beth points listeners to earlier conversations on reverse mortgages and using home equity as a retirement resource.
22:29 — Do remodels pay back dollar for dollar? The short answer: probably not. Kitchens and baths can run anywhere from $50K to $250K.
22:55 — Why the return on a remodel is only an estimate You don’t find out whether that $30,000 kitchen was worth $30,000 until the day you actually sell — potentially five years later, under entirely different market conditions.
24:18 — “Speed to selling” and buyer sentiment A dated kitchen may not cost you dollars directly — it may cost you time on market. Some buyers want turnkey; others want a project; others want to flip.
25:57 — Deferred maintenance and the lowball offer Homes that haven’t been cared for sit longer and attract price reductions.
27:12 — Is maintenance an expense or an investment? John’s answer: generally an expense, and the tax code likely agrees — but with real consequences at sale time.
28:46 — The nuance: maintenance affects value even as an expense Worn carpet, broken gutters, and visible neglect become counteroffer ammunition.
30:12 — Beth’s counterargument: stewardship Maintenance is an expense with an investment component. She frames herself as a steward of a property that will belong to someone else someday.
31:07 — The HVAC math $500/year in maintenance versus an unexpected $10,000 replacement — and the buyer who deducts $20,000 from their offer because the system is on its last legs.
31:58 — Off-season repair tip Beth’s practical aside: schedule work in the off season and avoid peak-demand pricing.
33:10 — The lifestyle return John’s central point: your stock and bond portfolio has no bed, no kitchen, no yard. Your home is simultaneously a financial asset and a lifestyle asset.
34:53 — Remodeling for life, not resale Beth’s own recent remodel — money she knows she won’t recoup, spent on a room that better fits this phase of life, and doesn’t regret.
36:10 — Air mattresses and lawn furniture John’s first-house furnishings, and the tradeoff between comfort investment and liquid investment.
37:57 — How to actually run an investment analysis on your home John outlines roughly seven to ten financial metrics and recommends running them two to four times per year — whether or not you’re thinking about selling.
38:37 — Metric one and two: purchase price, purchase date, current market value Your starting point and your assumed endpoint.
39:38 — Subtracting closing costs Agent commission, title and transfer costs, and any deferred maintenance you’ll have to fix as a condition of closing.
40:23 — Net cash after paying off the mortgage The worked example: $500K sale, minus $35K closing costs, minus remaining loan balance — what’s actually left.
41:57 — Tax basis and why it matters A $50K kitchen remodel likely steps up your basis from $250K to $300K, reducing taxable gain. Replacing carpet or painting likely does not.
43:31 — Takeaway #1: track your tax basis If you remember one thing from the episode, John says, make it this.
44:10 — Calculating percentage return — and then annualizing it A 40% total return over eight years is closer to 5–6% per year. Beth adds: now subtract maintenance and repairs across those years.
45:16 — When the financial number isn’t the deciding number Generational properties, family memories, and homes people never intend to sell.
46:31 — Risk profile: real estate versus the roulette wheel Homes carry relatively low risk of total loss — provided you live within your means and keep paying the mortgage.
48:02 — The 10-second social media take, dismantled Yes, you could earn more elsewhere. You could also lose far more. And none of those assets let you sleep, eat, or entertain.
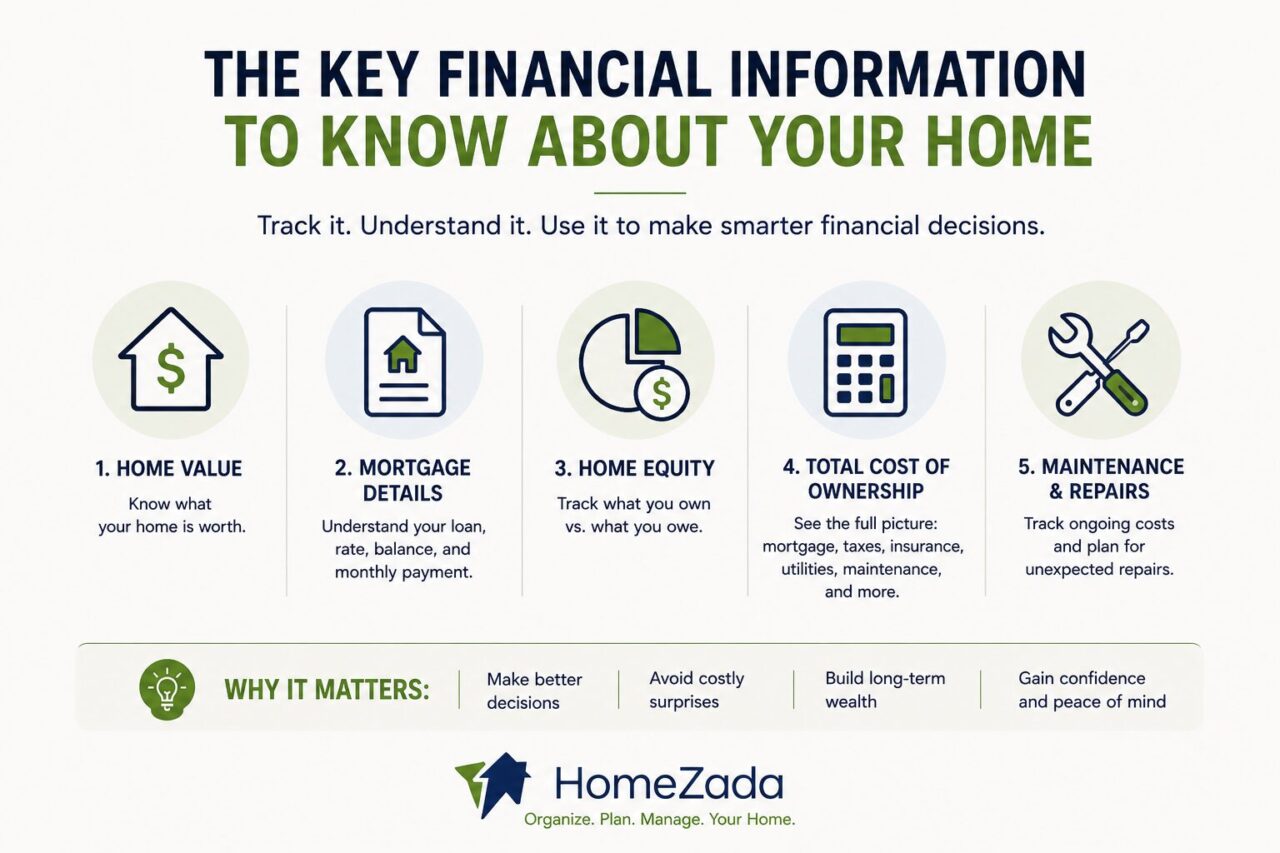
48:58 — Where the data actually lives Home value on one site, mortgage balance at your bank, remodel costs in a spreadsheet you forgot to update, HVAC service history nowhere. Scattered data is why most homeowners never run the analysis.
50:47 — Takeaway #2: build a system Whether it’s a spreadsheet or an application, document purchase price, purchase year, current value, mortgage balance, and tax basis — then check it two to four times a year.
51:35 — Does the analysis change your decisions? Renting out a room, funding a renovation after tuition ends, buying a second property, downsizing, or selling.
53:12 — The 25-year-old house problem Even with excellent maintenance, roofs and HVAC systems eventually need replacing. Do you fund the next ten years, or let the next buyer inherit it?
55:08 — Beth asks for the action items The “whiteboard session” close.
55:48 — John’s three steps (1) Aggregate your financial data — closing docs, major projects, current value, mortgage balance. (2) Learn the calculations, including net cash at sale and forecasting big-ticket replacements. (3) List the lifestyle projects you genuinely want to invest in.
57:09 — Beth’s addition: write down your lifestyle needs The story of friends who left a home they adored — 30 minutes from family, too much outdoor maintenance — for a smaller house and lot closer to the people they loved, accepting real inconvenience in the trade.
1:00:12 — Closing thoughts Your home is a financial asset, an expense, and a lifestyle asset all at once. No two homeowners are the same — decide for yourself.
KEY TAKEAWAYS
- Equity — not the online estimate — is the real number. Your home’s value is only half the equation. Current market value minus remaining principal tells you what you actually own.
- Track your tax basis religiously. Capital improvements like a kitchen remodel likely step up your basis and reduce taxable gain at sale. Repairs like paint and carpet likely don’t. If you keep one record, keep this one.
- Remodels rarely return dollar for dollar. A $30,000 kitchen doesn’t automatically add $30,000 in value — and you won’t know the real answer until the day you sell, under market conditions you can’t predict today.
- Remodels can still pay off in time-on-market. A dated kitchen may not cost you list price so much as it costs you months, especially with buyers who want turnkey.
- Maintenance is technically an expense — with real investment consequences. $500/year on HVAC service can prevent a $10,000 emergency replacement and a $20,000 haircut on your offer price. Deferred maintenance invites lowball offers.
- Your gross return isn’t your real return. A 40% gain over eight years annualizes to roughly 5–6% — and drops further once you subtract maintenance, repairs, interest, and taxes.
- Nobody analyzes risk, and they should. Higher-return investments carry higher potential for total loss. A home going to zero the day after you buy it is close to unthinkable.
- Closing costs and mortgage payoff come off the top. A $500,000 sale isn’t $500,000 in your pocket. Subtract agent commission, title and transfer costs, inspection-driven repairs, and your remaining loan balance.
- The lifestyle return is real and belongs in the analysis. Your stock portfolio has never fed anyone dinner. A remodel that doesn’t pay back financially can still be the right decision.
- Run the numbers two to four times a year. Not because you’re selling — because your value, equity, and life circumstances are all moving, and good decisions require current data.
- The hardest part is data collection. Home value, mortgage balance, project costs, and maintenance history live in four different places. Most homeowners skip the analysis for exactly this reason — a system solves it.
- Lifestyle needs change, and honesty about that is the whole point. Sometimes the smartest financial move is leaving a home you love for one that fits the life you’re actually living.
RESOURCES MENTIONED
- HomeZada — The home management application John co-founded, referenced as a way to consolidate purchase price, current value, mortgage balance, project costs, and maintenance history in one place, with the investment metrics calculated automatically.
- Your closing documents — The source of record for purchase price and purchase date, and the starting point for any investment analysis.
- Real estate portal / listing sites — Sources for current estimated market value (used as the endpoint of the analysis).
- Your mortgage lender statement or online account — For current principal balance.
- Your project and remodel records — Receipts, contracts, and invoices needed to establish tax basis.
- Previous episode: reverse mortgages — Referenced for listeners interested in accessing equity later in life.
- Previous episode with guest Rebecca: financial awareness of your home in retirement — Referenced for using home equity as a retirement resource.
- Your tax accountant or tax attorney — Recommended before undertaking remodels, and for any questions about basis, deductions, or capital gains.
CALL TO ACTION
Thanks for spending this hour with us on the Be a Smarter Homeowner Podcast.
If this conversation changed how you think about your home, here’s your assignment this week — John’s three steps:
- Gather your data. Pull your closing documents, list your major projects and what they cost, look up your current estimated value, and check your exact mortgage balance.
- Run the calculations. What would you net if you sold today, after closing costs and mortgage payoff? And what big-ticket replacements — roof, HVAC, water heater — are coming in the next ten years?
- Write down your lifestyle needs. Not just the projects you want. The life you actually want to live, and whether this house delivers it.
Do it two to four times a year, and you’ll make better decisions about every dollar that touches your home.
Please share this episode with another homeowner who’s wrestling with the buy, sell, remodel, or stay question. And if you haven’t already, subscribe so you don’t miss what’s next.
Until next time — stay proactive, stay organized, and remember: peace of mind starts at home.
This episode is for informational and educational purposes only. Beth Dodson and John Bodrozic are not financial advisors, tax professionals, or real estate agents. Please consult your own qualified professionals before making financial decisions.